SBA Financing Consulting
Prepare Before Underwriting
The earlier potential questions are identified, the more opportunity there is to address them before the financing request reaches formal review.
SBA Financing Consulting
Prepare Your SBA Financing Request Before It Reaches Underwriting
Frog Strategic Resource Consulting provides SBA financing consulting to help business owners and buyers evaluate opportunities, identify concerns, strengthen the transaction, and prepare for underwriting.
Even strong opportunities can face challenges if cash flow, borrower strength, structure, projections, or documentation do not clearly support the request. Our SBA financing consulting may include:
- Cash flow and debt service review
- Borrower and management strength
- Transaction structure and contribution
- Financial projections and assumptions
- Supporting documentation
- Pre-underwriting preparation
Why Preparation Matters
A Strong Business Still Needs a Strong SBA Financing Request
An SBA lender looks beyond revenue, credit, and the amount requested. Cash flow, borrower strength, repayment ability, transaction structure, and supporting financial information all influence how the request may be evaluated.
FSRC approaches SBA loan preparation from a lending and underwriting perspective, helping clients better prepare areas such as:
- Cash flow and debt service
- Borrower and management strength
- Transaction structure and contribution
- Financial statements and projections
- Sources and uses
- Supporting documentation
SBA Financing Opportunities
What Are You Trying to Accomplish?
SBA financing can support a variety of business objectives. FSRC helps evaluate the financial, structural, and documentation requirements surrounding the opportunity before financing is pursued.
Business Acquisition Financing
Review purchase price, business cash flow, buyer contribution, seller financing, working capital needs, and the overall acquisition structure.
Owner-Occupied Commercial Real Estate
Evaluate financing considerations for purchasing, constructing, improving, or refinancing property used by the operating business.
Business Growth & Expansion
Review capital requirements for new locations, expanded operations, additional capacity, or other business growth initiatives.
Equipment Financing
Evaluate equipment costs, available cash flow, borrower contribution, and how the investment fits within the broader financing request.
Working Capital
Consider operating capital needs, liquidity requirements, and how working capital should fit within the overall transaction structure.
Eligible Refinancing
Review existing obligations, cash flow, transaction purpose, and supporting information associated with an SBA refinancing opportunity.
SBA 7(a) & SBA 504 Financing
The Financing Program Should Fit the Opportunity
Not every SBA financing need is structured the same way. The appropriate program depends on the purpose of the financing, use of funds, transaction structure, borrower circumstances, and applicable lender and SBA requirements.
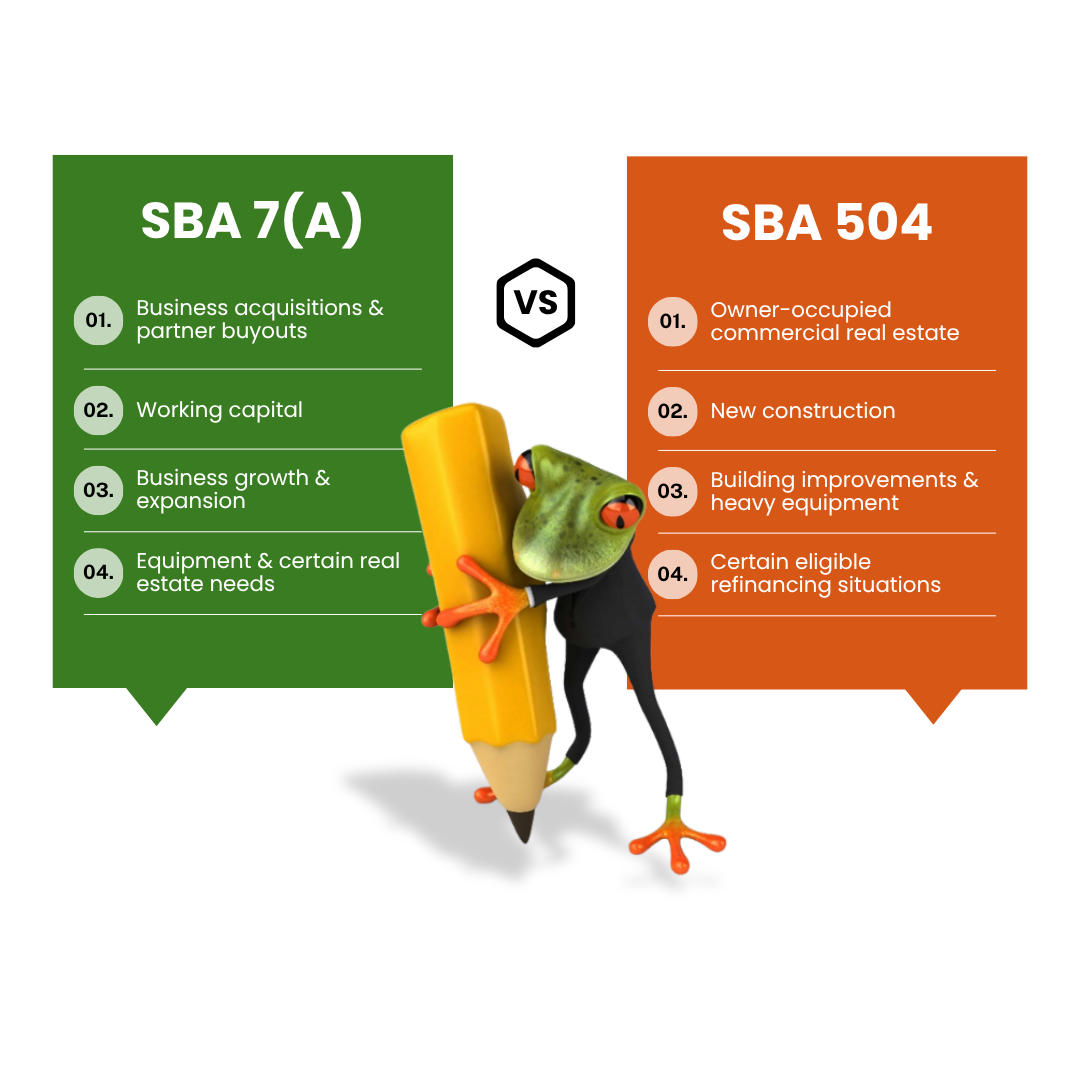
SBA 7(a) Financing
SBA 7(a) financing may support a range of business needs, from acquisitions and partner buyouts to expansion, equipment, working capital, and certain real estate opportunities.
The right use depends on the business objective, transaction structure, and applicable SBA and lender requirements.
- Business acquisitions and partner buyouts
- Working capital and business expansion
- Equipment and certain real estate needs
- Other eligible business purposes
SBA 504 Financing
SBA 504 financing may be used for qualifying fixed asset needs, including owner-occupied commercial real estate, construction, building improvements, heavy equipment, and certain refinancing situations.
FSRC helps clients evaluate and prepare the transaction based on the project, capital requirements, and financing structure, while final eligibility, underwriting, and approval remain subject to applicable lender and SBA requirements.
- Owner-occupied commercial real estate
- New construction and building improvements
- Long-term fixed assets and heavy equipment
- Certain eligible refinancing situations
Pre-Underwriting Review
Identify Potential Issues Before Formal Underwriting
Important financing questions are easier to address before the transaction is deep into lender review. FSRC brings a pre-underwriting review perspective to SBA financing to identify financial, structural, borrower, and documentation concerns earlier.
If an SBA financing request has stalled or raised questions, FSRC can also help identify what may need attention before the opportunity is presented again. Our review may focus on:
- Historical cash flow and repayment capacity
- Debt service requirements
- Financial performance and projections
- Borrower liquidity and financial strength
- Management and industry experience
- Ownership and guarantor considerations
- Borrower contribution and sources and uses
- Seller financing, when applicable
- Supporting documentation
- Potential underwriting concerns
Understanding the Opportunity
The Numbers Need Context
An SBA financing request is more than financial statements and forms. Lenders also need to understand the business, borrower, purpose of the financing, and transaction behind the numbers. FSRC helps bring those pieces together so the SBA financing request presents a clearer financial and transaction story.
The Business
Understand operations, historical performance, and management.
The Opportunity
Clarify why financing is needed and what the borrower wants to accomplish.
The Financial Picture
Evaluate cash flow, projections, liquidity, and repayment support.
The Transaction
Define what is being purchased, acquired, built, expanded, or refinanced.
The Capital Structure
Understand how much capital is needed, where it comes from, and how it will be used.
The Borrower
Consider experience, financial strength, ownership, and contribution.
Business Objective
- Acquire a business
- Expand operations
- Purchase equipment
- Acquire real estate
- Refinance eligible debt
Complete Transaction
- Purchase or project costs
- SBA financing
- Complete sources and uses
- Seller financing, when applicable
- Working capital
- Borrower equity
Repayment Strategy
- Historical cash flow
- Projected performance
- Debt service requirements
- Borrower contribution
- Long-term sustainability
SBA Transaction Structuring
The Loan Amount Is Only One Part of the Transaction
A borrower may begin with a specific SBA loan amount in mind, but the financing strategy should reflect the entire transaction.
FSRC evaluates the business objective, financial position, capital requirements, and transaction structure to determine what may best support the borrower’s goals.
- SBA financing
- Borrower equity
- Seller financing
- Working capital
- Acquisition costs
- Real estate or equipment costs
- Sources and uses
- Debt service requirements
- Financial projections
- Other capital considerations
SBA Loan Package Preparation
Prepare the Opportunity for Lender Review
Once the financing strategy and transaction structure are clearer, the next step is making sure the SBA financing request is supported by organized, credible information.
FSRC provides SBA loan package preparation and financial documentation support to help communicate the business, borrower, transaction, use of funds, and financial story more clearly. Depending on the engagement, preparation may include:
- Historical financial statements
- Interim financial information
- Financial projections and assumptions
- Debt schedules
- Sources and uses
- Business plans
- Financial narratives
- Management and ownership information
- Transaction summaries
- Supporting financial documentation
- Loan and capital package preparation
We Work on the Deal Before We Work on the Financing.
Why FSRC
SBA Preparation With a Lender’s Perspective
FSRC does not approach SBA financing as simply completing an application and searching for a lender. We work to understand and strengthen the transaction before financing is pursued.
- 25+ Years of Lending Experience: Apply firsthand lending knowledge to the financial, structural, and underwriting questions surrounding the SBA financing opportunity.
- Pre-Underwriting Perspective: Identify potential financial, documentation, borrower, or transaction concerns before they become larger issues during formal review.
- Transaction-First Strategy: Look beyond the requested loan amount to understand what the business and transaction may actually require.
- Financial Preparation: Help organize the financial information, projections, transaction details, and supporting documentation behind the financing request.
Tell Us About Your SBA Financing Need
Better Preparation Starts With a Conversation
Tell us about your acquisition, owner-occupied real estate, expansion, equipment, working capital, refinancing, or other SBA financing need. FSRC will review the opportunity and determine whether our SBA financing consulting and SBA loan preparation experience may be able to help.